Learn how cost segregation studies can help property owners identify accelerated depreciation opportunities following construction, renovation, or expansion projects.
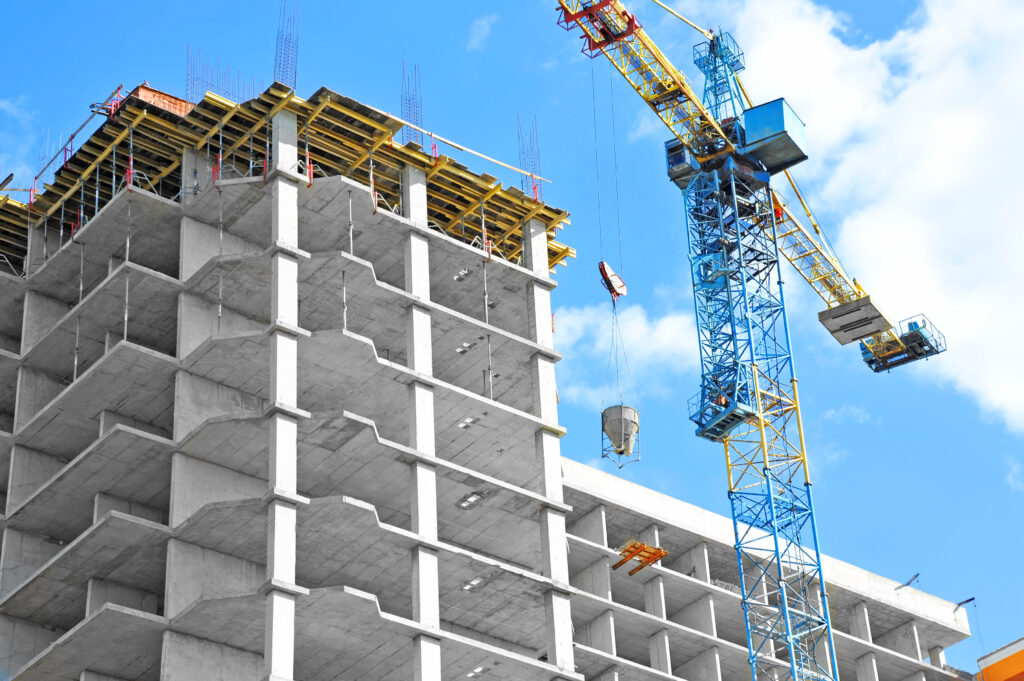
Construction, renovation, and expansion projects can create significant tax planning opportunities, especially when large portions of project costs are initially assigned to a building’s long depreciation life. These opportunities often arise because construction-related costs are initially grouped into the building as a whole, even though certain components of the project may qualify for shorter depreciable lives.
A cost segregation study can help identify components of newly constructed, acquired, or renovated property that may qualify for shorter depreciation recovery periods and, in some cases, accelerated depreciation deductions. When completed, the study can improve after-tax cash flow and support broader financial goals.
What is a cost segregation study?
A cost segregation study analyzes acquired, constructed, or renovated property and allocates its depreciable basis among the appropriate asset classes. Its primary purpose is to identify shorter-lived assets that may qualify for accelerated depreciation. For purposes of construction planning, a cost segregation study can be especially useful when a taxpayer has recently completed, or is planning, a new construction, renovation, expansion, or tenant build-out.
Why construction projects create opportunities
When a commercial or residential building is placed into service, the entire project cost is often grouped into a single building asset and depreciated over a long recovery period. Nonresidential real property is depreciated over a period of 39 years, while residential rental property is depreciated over a period of 27.5 years.
Construction projects often include more than the building structure itself. Not all project costs must be recovered over these longer periods, particularly when construction and renovation projects include equipment, specialized buildouts, or site improvements. These assets may instead qualify as 5-,7-, or 15-year property.
Within a construction project, shorter-lived assets may include:
- Section 1245 personal property – equipment, furniture, fixtures, removable assets
- Land improvements – parking lots, sidewalks, fencing, landscaping improvements
- Qualified improvement property for eligible interior improvements to existing nonresidential buildings
Classifying these assets into shorter recovery periods can accelerate depreciation deductions and reduce taxable income earlier in the property’s life. Additionally, in some cases, these identified shorter-lived assets may also be eligible for bonus depreciation or Section 179 expensing. In these situations, assets could potentially be fully expensed within their first year of service, if the applicable requirements and limitations are met.
These studies do not change the overall depreciable basis of the property but instead change the timing of the depreciation deductions. The result is often larger depreciation deductions earlier in the property’s life. By accelerating deductions into earlier tax years, a taxpayer may reduce current taxable income and improve after-tax cash flow. Access to those tax savings earlier may help property owners preserve working capital, fund future improvements, create additional planning flexibility, and support other broader financial goals.
When a study may make sense
Cost segregation studies are often considered for properties with significant construction, renovation, and expansion costs. These studies are often most beneficial for properties with construction costs exceeding $1 million.
Examples of these projects include:
- Office buildings
- Hotels
- Apartment complexes
- Warehouses and distribution centers
- Manufacturing facilities
Generally, this threshold is a good rule of thumb but does not necessarily mean that a cost segregation is not still a good opportunity for smaller projects. Even for smaller projects, evaluating whether there is a higher concentration of shorter-lived assets may help determine whether a cost segregation study would provide meaningful benefits.
Documentation matters
A cost segregation study should be supported by reasonable and well-documented asset allocations and records, including invoices, construction records, and contractor documentation. These documents are more easily accessible near the end of a project or shortly after completion, which can provide more support and detailed information for the cost segregation study. The best time to gather support is during or shortly after the construction project, when these items are still readily available.
At Keiter, our cost segregation engagements utilize an engineering-based methodology supported by a site visit, detailed workpapers, and appropriate documentation. We work alongside experienced construction engineering professionals to help identify qualifying assets and support the study’s conclusions.
Key takeaway
A cost segregation study can be a valuable tool for construction projects on nonresidential and residential properties by identifying accelerated depreciation opportunities and improving after-tax cash flow. By classifying building components, personal property, and land improvements during or shortly after construction, taxpayers may be able to accelerate depreciation deductions and realize tax savings earlier in the property’s life.
For taxpayers acquiring, constructing, renovating, or expanding real estate, a cost segregation study may provide meaningful tax and financial planning opportunities.
If your organization is constructing, expanding, or renovating a commercial or residential property with project costs exceeding $1 million, a cost segregation study may be an opportunity for you to help support your financial objectives.
Contact Keiter’s Cost Segregation Team to discuss your construction project and determine whether a cost segregation study may be appropriate for your situation.
About the Author
The information contained within this article is provided for informational purposes only and is current as of the date published. Online readers are advised not to act upon this information without seeking the service of a professional accountant, as this article is not a substitute for obtaining accounting, tax, or financial advice from a professional accountant.