By Tianna Wooldridge, CPA , Business Assurance & Advisory Services Manager
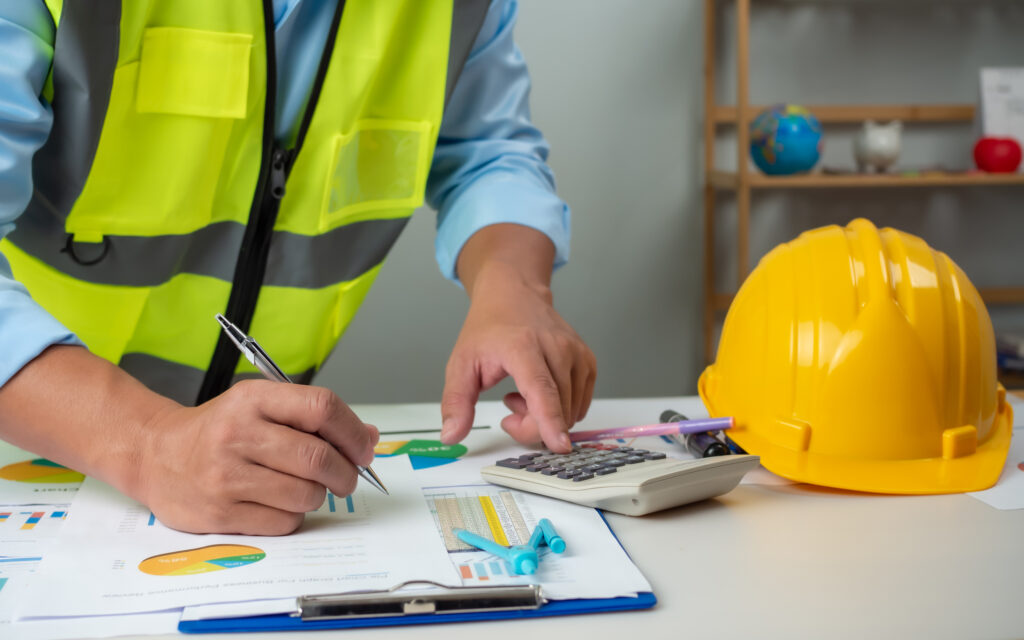
Strong accounting controls help construction companies manage contract costs, improve financial reporting, and protect profitability.
In the construction industry, managing contract costs is a complex task that requires rigorous accounting controls. For Construction Finance Leaders (CFO, Controller, Accounting Manager) understanding and implementing these controls are crucial to ensure financial accuracy, mitigate risks, and enhance profitability.
Importance of accounting controls for contract costs
Accounting controls for contract costs are procedures that ensure the accuracy and reliability of cost information related to construction contracts. These controls help in preventing errors, detecting irregularities, and managing costs effectively. In the construction industry, where projects often involve significant costs and numerous transactions, strong accounting controls are particularly important.
Key accounting controls for contract costs
- Cost Estimation and Budgeting
Cost estimation and budgeting is the first step in controlling contract costs. It involves estimating the costs of labor, materials, equipment, and other resources needed for a project. These estimates should be based on detailed analysis and should be regularly reviewed and updated as the project progresses. It is important to keep an accurate analysis of the cost estimates as these numbers should be updated on the company’s WIP (Work in Progress) schedule, which ultimately flow to the face of the financial statements.
- Cost Allocation
Cost allocation involves assigning costs to specific contracts or projects. This process should be based on clear and consistent criteria to ensure that costs are allocated accurately. Most accounting software has a way to track specific job costs and can establish a method to allocate indirect or overhead costs to jobs. However, be sure to implement a control to review those allocations.
- Cost Monitoring and Reporting
Cost monitoring and reporting involves tracking actual costs against budgeted costs and reporting any variances. This process should be done regularly to provide timely information for decision-making and financial reporting. This process will also prepare the Company for audit/review time when the CPA firm asks for specific explanations behind material variances in the job’s gross profit/loss margin when performing year over year comparison procedures.
- Change Order Management
Change order management involves controlling costs related to changes in the scope of work. All change orders should be properly documented and approved before the work is carried out. Be sure to reflect change orders (whether additional or deductive) on the Company’s WIP schedule.
- Use of Accounting Software
Modern accounting software can automate many cost accounting procedures, reducing the risk of human error. It can also provide real-time cost data, helping Construction Financial Leaders make informed decisions within a reasonable period of time. The accounting software can also produce a preliminary WIP schedule. Be sure to review that schedule periodically to ensure it is capturing the correct information.
Strengthening financial performance through effective cost controls
Implementing robust accounting controls for contract costs is a critical task for Finance Leaders in the construction industry. By focusing on cost estimation and budgeting, cost allocation, cost monitoring and reporting, change order management, and the use of accounting software, these leaders can effectively control contract costs, enhance profitability, and contribute to the success of their companies. Remember, effective cost control is not just about minimizing costs; it’s about maximizing value for every dollar spent and being able to report accordingly.
Contact Keiter’s Construction Opportunity Advisors to learn how we can help your business strengthen accounting controls and improve financial performance.
About the Author
Tianna Wooldridge, CPA , Business Assurance & Advisory Services Manager
Tianna is a Manager on the Business Assurance and Advisory Services team. She specializes in real estate and construction, non-profit organizations, and tax credits and is an active member of both the Real Estate and Construction and Not-for-Profit niche groups.
More Insights from Tianna WooldridgeThe information contained within this article is provided for informational purposes only and is current as of the date published. Online readers are advised not to act upon this information without seeking the service of a professional accountant, as this article is not a substitute for obtaining accounting, tax, or financial advice from a professional accountant.